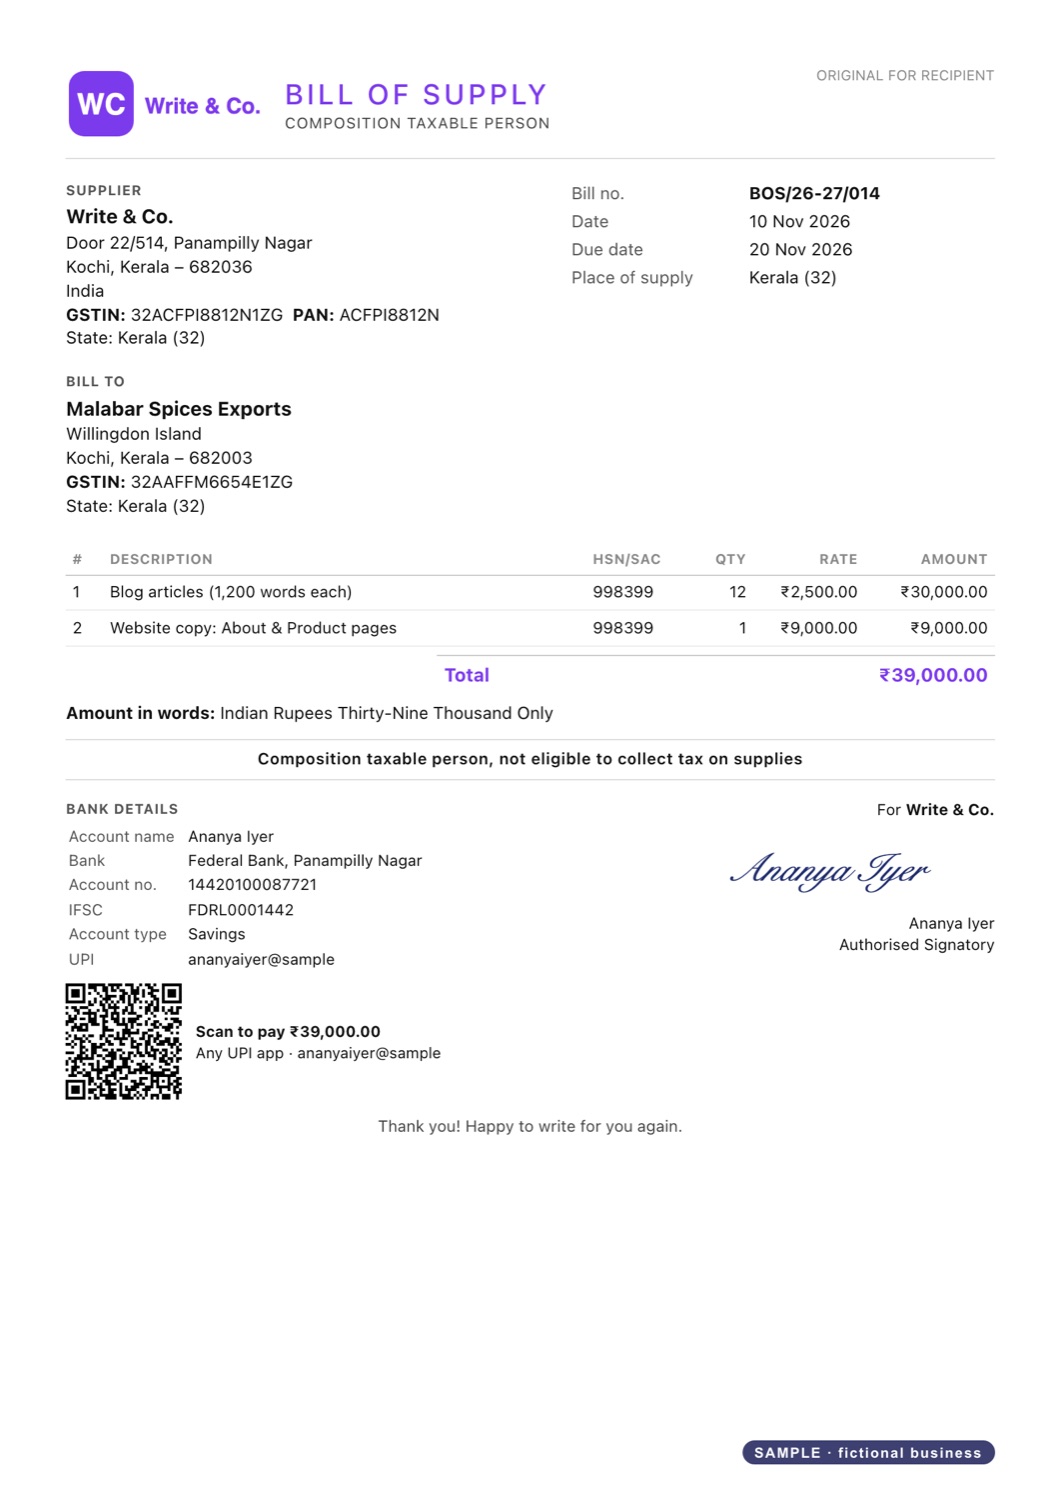
When to use a bill of supply
- You're registered under the composition scheme. Composition dealers pay tax at a flat rate on turnover and can't collect GST from customers, so every sale is on a bill of supply.
- You sell exempt goods or services, such as fresh vegetables or some healthcare and education services, even if you're a regular taxpayer.
If you sell both taxable and exempt items to the same customer, you can issue a single invoice-cum-bill of supply.
Mandatory fields (Rule 49)
- Your name, address and GSTIN.
- A consecutive serial number of up to 16 characters, unique for the financial year.
- Date of issue.
- Customer's name, address and GSTIN if registered.
- HSN or SAC code.
- Description of the goods or services.
- Value after any discount.
- Your signature or digital signature, or that of someone you authorise.
Composition dealers must also print this line at the top of the bill: “composition taxable person, not eligible to collect tax on supplies”.
Bill of supply vs tax invoice
| Tax invoice | Bill of supply | |
|---|---|---|
| Charges GST | Yes | No |
| Tax rate and amount shown | Yes | No |
| Who issues it | Regular taxpayers on taxable sales | Composition dealers, and anyone on exempt sales |
| Customer can claim input tax credit | Yes | No |